
Cash & short-term reserves
Money for near-term spending and flexibility.
Compare access, yield, inflation risk and the protection that actually applies. A money market fund is not a bank deposit.

Eberst expertise
One financial life, considered together. Your income, investments and family priorities belong in the same conversation. We help you see how the decisions connect.
The purpose behind the plan
A life after work. A portfolio with a purpose. Care for the people who depend on you. Bruce Eberst brings these questions into a personal planning conversation, with a team you can get to know.
Life after work
How do I turn what I’ve built into the life I want?
A clearer picture of your income sources, planning assumptions, and decisions to review as life changes.
Retirement changes the question from how much you can accumulate to how your resources can support your life. We bring spending, Social Security, pensions, and investments into one planning conversation.
For people approaching retirement, adjusting to life after work, or revisiting an income plan after a household change.
A retirement income overview. Discuss a written overview that brings income sources, spending priorities, planning assumptions and unresolved decisions into one place. Agree the scope and format with Bruce before engaging.
Agree when your income plan will be revisited and what information you will receive. Ask how changes in spending, income or withdrawal needs will be handled between scheduled reviews.
Purpose in your portfolio
Does every part of my portfolio have a purpose?
An investment approach you can understand, with an agreed purpose and a clear review process.
An investment strategy should reflect the life it is intended to support. We consider your objectives, capacity for risk, time horizon, liquidity needs, and account structure together.
For people who want an ongoing conversation about how their portfolio supports retirement, near-term needs and longer-term goals.
A portfolio purpose review. Discuss a written review connecting your objectives with account roles, risk exposures, liquidity needs and investment costs. Agree which accounts and decisions are within the engagement.
Agree the portfolio review schedule, the reporting you will receive and how decisions or changes will be discussed. Clarify which accounts are covered and how to raise a time-sensitive question.
The people around your wealth
How can my wealth care for the people who matter?
An organized set of protection priorities and professional conversations, grounded in the documents and coverage you actually have.
Protection and legacy planning start with your priorities. We help you review existing coverage and beneficiary arrangements, and coordinate financial questions with your attorney and accountant.
For families reviewing protection needs, existing life insurance or financial responsibilities after a change in circumstances.
A protection and family priorities summary. Discuss an organized summary of existing coverage, beneficiary questions and actions to coordinate with other professionals. Agree which records and financial questions the review will cover.
Agree how protection needs and beneficiary questions will be revisited. Ask who to contact after a family change, a policy notice or a change in financial responsibilities.
Early retirement planning
Thinking about leaving work before traditional retirement ages? Explore the bridge between your last paycheck, account-access rules, Social Security and Medicare.
The larger picture
An investment decision can affect income and liquidity. A family transition can change protection needs. We consider those relationships and coordinate financial questions with your qualified legal and tax professionals.
Understand the tools
A broad range of investments and insurance can address different needs. Use these categories to ask better questions—not as a shopping list or a recommendation. Individual product access depends on platform availability, eligibility, licensing and your circumstances.
Money for near-term spending and flexibility.
Compare access, yield, inflation risk and the protection that actually applies. A money market fund is not a bank deposit.
Income and a defined role in the portfolio.
Compare issuer credit quality, maturity, interest-rate sensitivity and the risk of selling before maturity. Bond funds do not work exactly like a bond held to maturity.
Participation in markets and different ways to build a portfolio.
Compare holdings, diversification, volatility, expenses and trading costs. A fund label alone does not tell you how much risk it takes.
An investment approach within an agreed advisory relationship.
Clarify the strategy, account coverage, decision authority, advisory fees, underlying expenses and reporting. Management does not guarantee performance.
Contractual income or other insurance features where appropriate.
Compare fixed, indexed and variable structures, surrender terms, riders, fees and insurer obligations. Some expose you to market losses; guarantees depend on the insurer.
Financial protection for the people and responsibilities that matter.
Compare term and permanent coverage, premiums, exclusions, underwriting and cash-value assumptions. Policy loans or withdrawals can affect coverage and tax treatment.
A structure for saving toward family goals.
Compare ownership, beneficiaries, eligible uses, investment choices and tax treatment. Account features and limits can differ from the investments held inside them.
Specialized exposures with additional complexity.
Examine eligibility, valuation, leverage, issuer risk, fees and redemption limits. Limited liquidity can conflict with money needed for an early retirement bridge.
Learn about product features and risks directly from the sources:
SEC Investor.gov: investment productsFINRA: alternative and emerging productsNAIC: life insuranceLPL describes a broad product platform. That platform description is not confirmation that every product is available through Bruce or appropriate for a particular client. Review LPL’s product overview.
Fees & transparency
Know what you pay. Understand what you receive.
Compensation can include asset-based advisory fees, commissions on insurance and certain securities products, and planning fees, depending on the engagement. Different arrangements can create different incentives.
Review LPL Financial’s disclosures, including Form CRS and the applicable advisory brochure. Our disclosures page explains the relationship and important limitations.
Investing involves risk. Diversification does not assure a profit or protect against a loss. Annuity guarantees depend on the issuing insurer’s claims-paying ability. Eberst and LPL do not provide tax or legal services.
A person at the center
Your questions deserve context. Your decisions deserve a conversation.
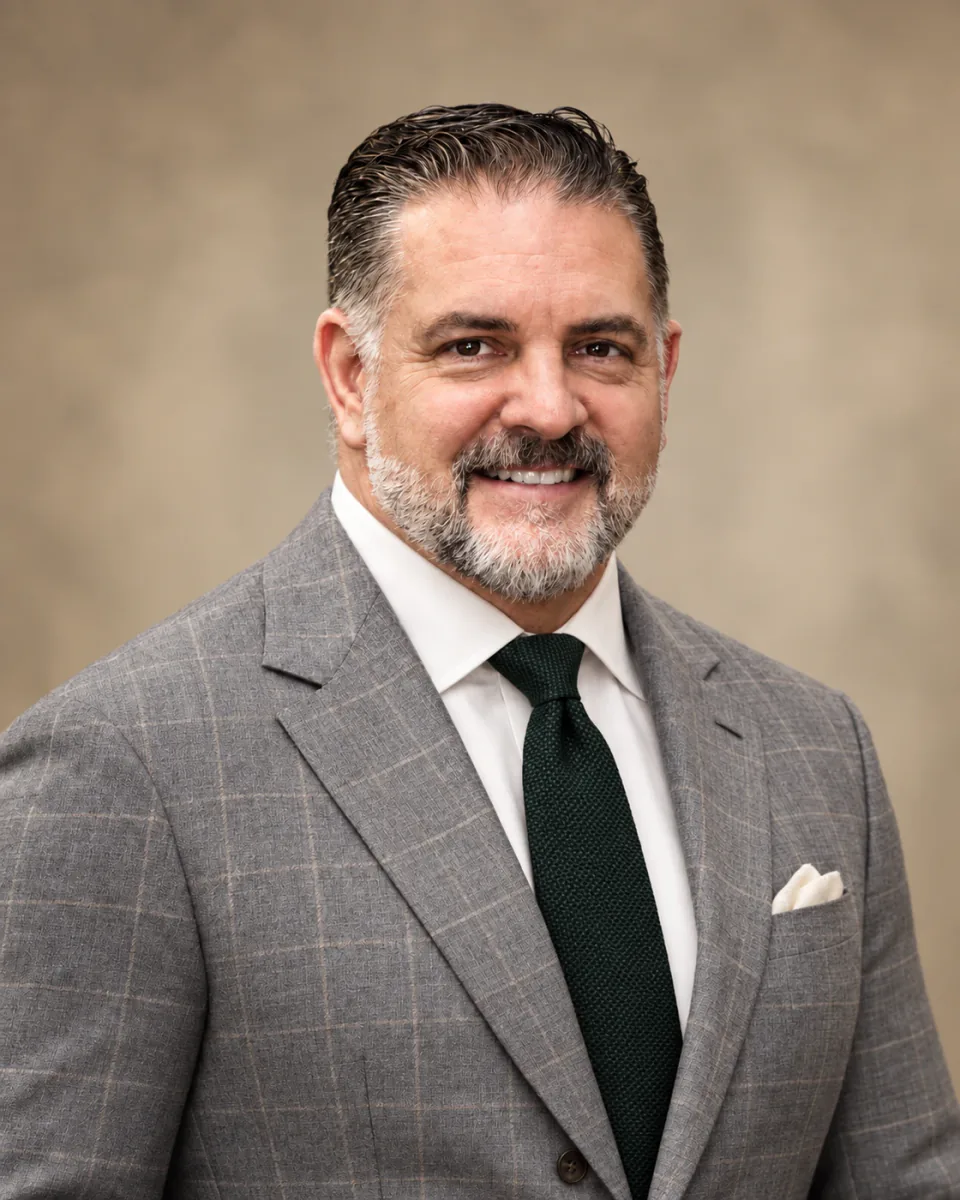
Bruce leads the practice with a personal perspective on retirement income, investments and the financial questions families face. The first step is to understand what brought you here and what you want your wealth to support.
We can begin with your priorities, upcoming decisions and what you would find useful in an advisory relationship. If we agree to continue, we’ll discuss the relevant information and next steps.