
The life your income supports
Separate everyday spending from flexible goals and larger future expenses. Identify which costs need dependable funding and which choices can change.
Retirement income planning · Boca Raton
Connect the retirement you imagine with the income, investments and decisions that may support it. Start with your household, your priorities and the questions ahead.
A personal first conversation. No obligation to continue.
When this conversation matters
For people approaching retirement, adjusting to life after work, or revisiting an income plan after a household change.
The work behind the decisions
Separate everyday spending from flexible goals and larger future expenses. Identify which costs need dependable funding and which choices can change.
Bring Social Security, pensions, employment income and investment accounts into the discussion. Review timing questions in the context of your household.
Discuss inflation, market declines, a longer retirement and unexpected spending. Explore the assumptions behind any illustration and the choices you would revisit.
A written scope to discuss
Discuss a written overview that brings income sources, spending priorities, planning assumptions and unresolved decisions into one place. Agree the scope and format with Bruce before engaging.
What to ask the work to address
Specific deliverables, timing and fees are agreed for your engagement.
An ongoing conversation
Agree when your income plan will be revisited and what information you will receive. Ask how changes in spending, income or withdrawal needs will be handled between scheduled reviews.
How we approach the relationshipBefore engaging, agree the regular review frequency, who to contact between meetings and the work included in your fee.
Something useful before we meet
Use this service-specific conversation worksheet to organize your thoughts. No sign-up or account information is required.
Download the conversation worksheet (PDF)A preparation guide for you—not a completed financial plan.
Understand retirement incomeKeep your initial message general. If you decide to continue, agree an appropriate way to share financial documents.
Before you decide
No. The conversation can begin while you are still working, as a retirement date approaches, or when an existing plan needs a fresh look.
The first conversation is about your needs and whether there is a fit. Any account arrangements, services and fees should be discussed before you decide to proceed.
These income sources can be part of the planning conversation. Bring the timing or election decisions you face and ask what analysis would be included in your engagement.
Compensation can include asset-based advisory fees, insurance and certain securities commissions, and planning fees. Ask which arrangements apply to you, what work is included and what potential conflicts to consider.
Income illustrations depend on assumptions and do not guarantee results. Investment values can fall. If an annuity is discussed, review its costs, restrictions and the issuing insurer’s claims-paying ability.
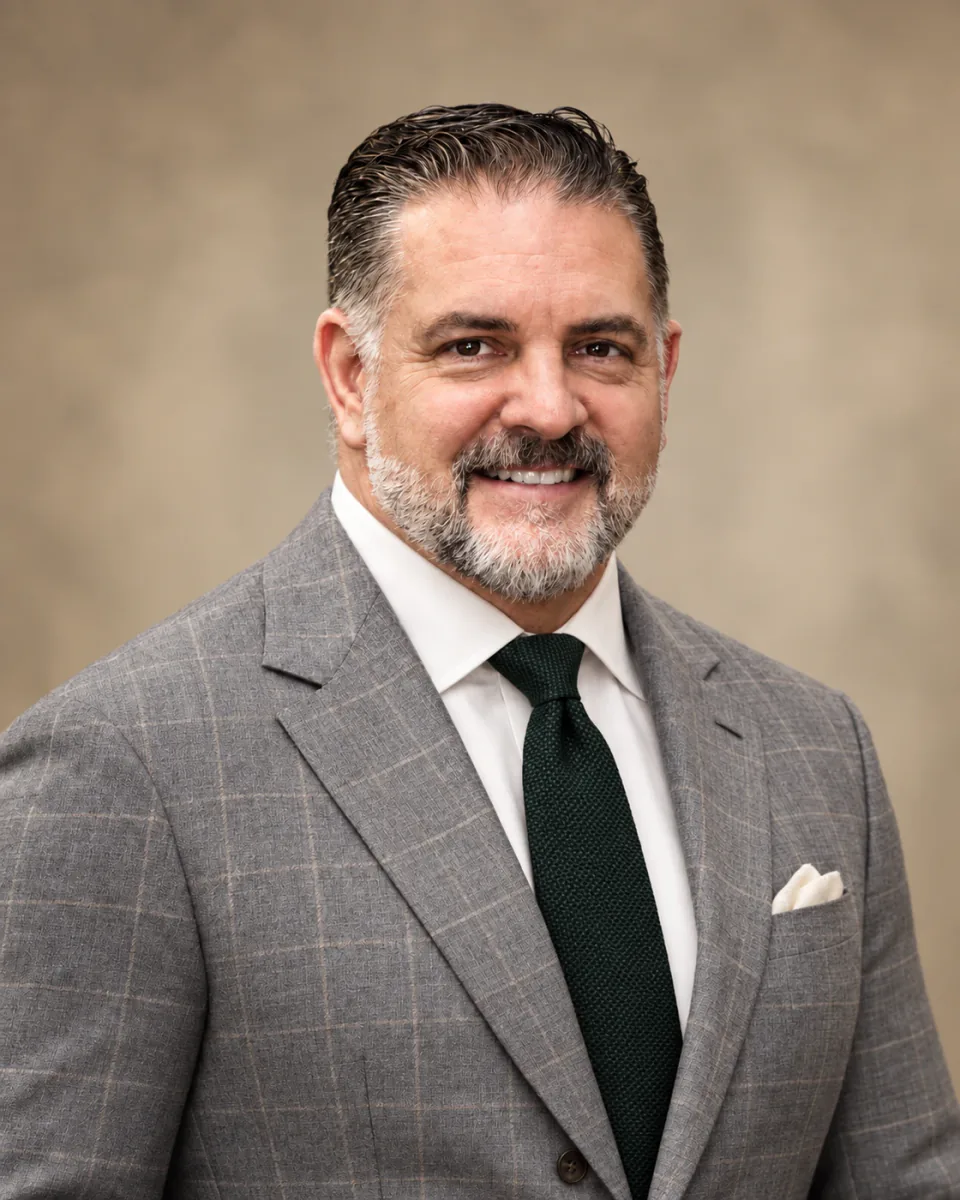
The person behind the conversation
Bring Bruce your priorities and the decisions you face. Discuss whether the service fits your needs, what the work would include and how you would keep the conversation going.
Bruce Eberst is a registered representative of LPL Financial and has been with LPL Financial since 2009. Securities are offered through LPL Financial, member FINRA/SIPC. Investment advisory services are offered through Independent Advisor Alliance, LLC, a registered investment adviser. Eberst Wealth Management, Inc. and Independent Advisor Alliance are separate entities from LPL Financial.
Talk with BrucePublic records list Robert Bruce Eberst Jr., CRD 2656135. For clients outside Florida, service availability depends on registration and licensing.